
Unlock Capital Without Selling Assets
SBLC monetization stands as a core tool for businesses that hold a standby letter of credit and need immediate liquidity. At TRG Venture Capital International Investment G.P. Limited we see clients use this process every day to fund projects, expand operations, and bridge cash-flow gaps. This guide covers the full process, legal boundaries, real structures that work, and the exact steps that produce results.
A standby letter of credit, or SBLC, is a bank’s independent undertaking to pay a named beneficiary if the applicant fails to perform. It is not a cash deposit. It is a contingent promise governed most often by ISP98. Monetization turns that promise into usable funds by pledging the instrument as collateral for a loan or credit facility. The SBLC stays in place for its original purpose while the holder receives a percentage of face value as cash or credit.
TRG Venture Capital International Investment G.P. Limited specialises in this exact service. We arrange verified instruments from top-tier banks and structure monetization facilities that meet strict compliance standards. Our clients receive capital within days once the instrument clears verification.
What SBLC Monetization Actually Involves
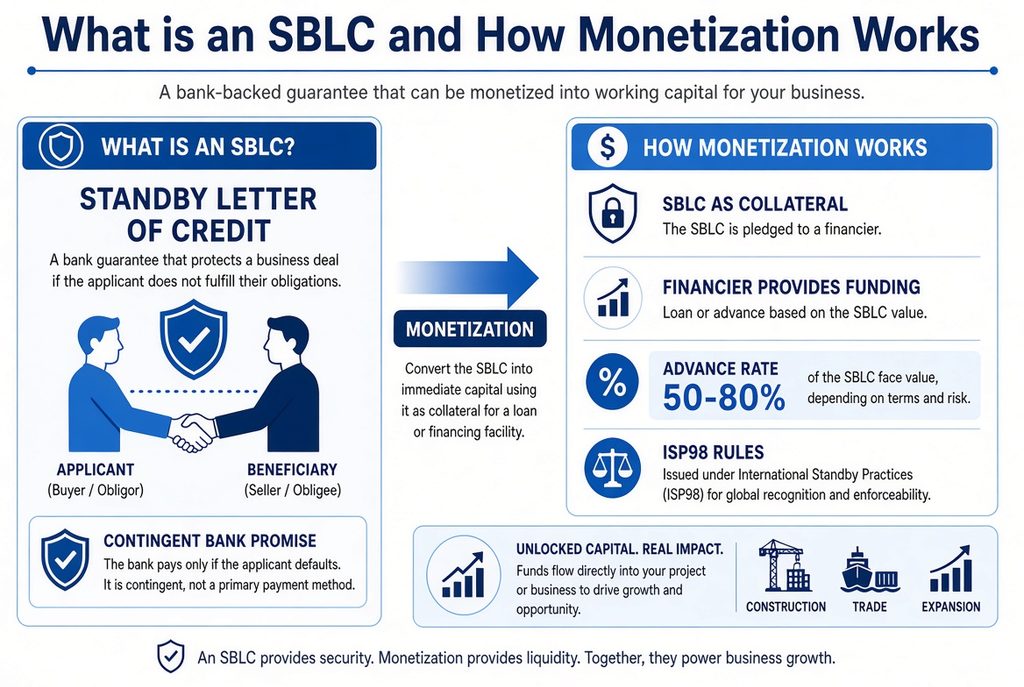
Monetization is not the sale of the SBLC. It is not a trading programme. It is a secured financing arrangement. A lender or fund accepts the SBLC, confirms its authenticity through SWIFT MT760, assesses the issuing bank’s credit rating, reviews the wording, and advances funds against it. Advance rates typically fall between 50 percent and 80 percent of face value. The exact percentage depends on bank rating, remaining tenor, governing rules, and the strength of the underlying commercial obligation.
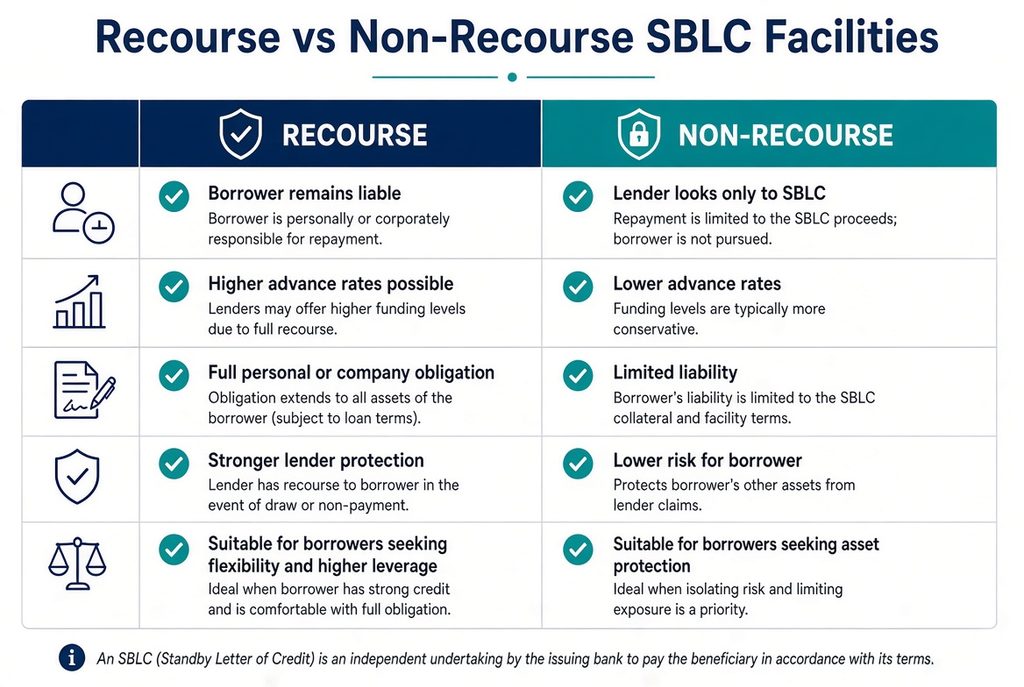
Two structures dominate legitimate deals. In a recourse facility the borrower remains liable for repayment if the SBLC is not drawn or the issuer fails. In a non-recourse facility, the lender looks only to the SBLC for recovery. Non-recourse terms produce lower advance rates because the lender absorbs more risk. Most institutional lenders prefer clear repayment sources beyond the instrument itself. Project cash flows, offtake contracts, or receivables assignments strengthen the package.
The process begins with a genuine bank-issued SBLC. Leased instruments raise red flags. Regulators including the SEC have repeatedly warned that leased SBLC programmes often form part of prime bank fraud schemes. We at TRG Venture Capital International Investment G.P. Limited insist on owned or properly collateralised instruments from rated banks. Verification happens only through authenticated SWIFT channels. No screenshots or PDF copies substitute for a live MT760.
Step-by-Step SBLC Monetization Process
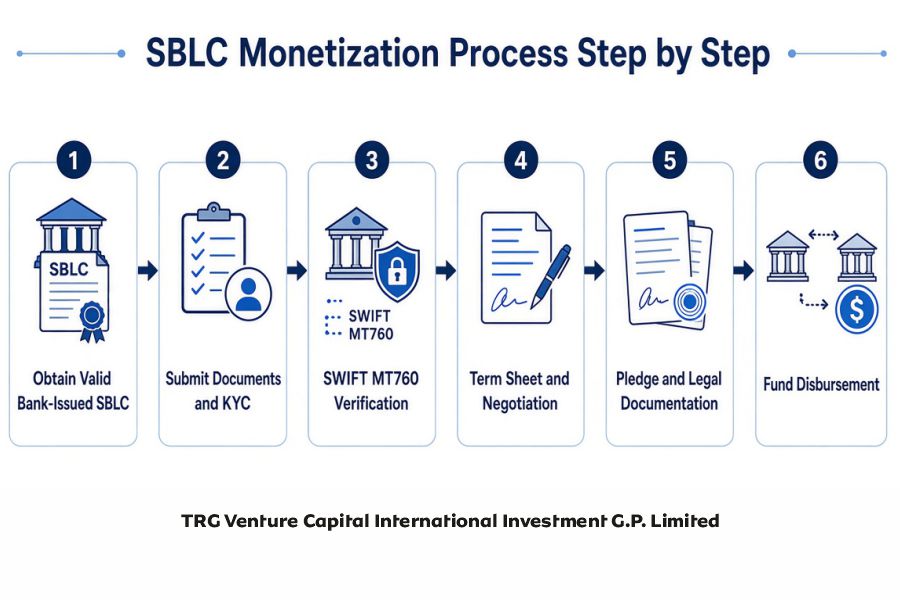
First the holder presents the instrument and supporting documents. These include the full SWIFT text, applicant details, beneficiary information, expiry date, and the commercial contract the SBLC supports. TRG Venture Capital International Investment G.P. Limited runs full KYC and AML checks at this stage. We confirm the issuing bank’s rating and the instrument’s compliance with ISP98 or UCP 600.
Next comes formal verification. The monetizer’s bank contacts the issuing bank via SWIFT. Only after the issuing bank confirms the details does the process move forward. This step eliminates most fraudulent instruments.
Once verified, the parties negotiate terms. Key points include advance rate, interest or discount, facility tenor, repayment schedule, and security package. TRG Venture Capital International Investment G.P. Limited prepares a clear term sheet that lists every fee and condition. Clients know the net proceeds before they commit.
Documentation follows. The SBLC is assigned or pledged according to its transfer and assignment clauses. Legal opinions confirm enforceability. Funds are then disbursed according to the agreed schedule. Many facilities release capital in stages linked to project milestones.
Throughout the process we maintain transparency. Clients receive status updates at each milestone. We never request engagement fees or due-diligence payments before the instrument is live and verified.
Real-World Example
Sometime ago an infrastructure developer held a €25 million SBLC issued by a top-20 European bank under ISP98. The instrument supported a performance obligation on a renewable energy project. Therefore, construction costs exceeded initial forecasts and the developer needed €15 million within three weeks to keep contractors on site.
After searching for a trust worthy provider in vain the developer approached TRG Venture Capital International Investment G.P. Limited. We verified the MT760 within four business days. The facility was structured as a 12-month non-recourse advance at 65 percent of face value. Net proceeds reached €15.8 million after fees. The developer used the capital to complete the next construction phase. Project revenues later repaid the facility without drawing on the SBLC. Since then, he’s been referring people to TRG Venture Capital International Investment G.P. Limited earning 10% commission for his successful referrals.
The instrument remained available for its original purpose until expiry.
Legal and Compliance Boundaries
SBLC monetization sits inside ordinary secured lending. It is legal when the instrument is authentic, the wording permits assignment or transfer, and the parties complete proper due diligence.
Investopedia provides a clear definition of the instrument itself and its traditional role in trade. We recommend every client review that material before starting any monetization discussion.
ISP98 rules govern most modern standbys. These rules set precise standards for presentation, examination, and notice of dishonour. Weak wording reduces advance rates or blocks monetization entirely. TRG Venture Capital International Investment G.P. Limited reviews every instrument against ISP98 standards before committing capital.
Case Study: Manufacturing Expansion in Asia
In 2024 when an electronics manufacturer in Asia needed working capital to fulfil a large export order the company held a $40 million SBLC from a regional bank that was acceptable to international lenders but traditional bank loans required additional hard collateral the company did not want to pledge.
TRG Venture Capital International Investment G.P. Limited structured a monetization facility. After SWIFT confirmation and legal review we advanced 70 percent of face value on a recourse basis with a clear repayment schedule tied to export receivables. The company received $27.5 million net. It paid suppliers, shipped the goods, collected payment, and repaid the facility within nine months. The SBLC continued to support the company’s credit profile with its main buyers. The transaction closed in eleven business days from first contact.
These outcomes are possible only when every party follows documented banking practice
Benefits That Matter to Businesses
Businesses choose SBLC monetization for speed. Traditional loans often take months. Verified instruments can produce funds in under two weeks. They also preserve equity. Owners avoid dilution. They keep the original guarantee in place for commercial counterparties. The capital can fund inventory, construction, acquisitions, or refinancing without selling core assets.
At the same time the process carries costs. Advance rates sit below 100 percent. Interest or discount rates reflect the risk of the issuing bank and the structure. Legal and arrangement fees apply. Clients must weigh these costs against the value of immediate liquidity.
Common Pitfalls and How to Avoid Them
Many enquiries fail because the instrument is not transferable or the assignment of proceeds is restricted. Others fail because the remaining tenor is too short. Still others fail because the underlying commercial contract lacks substance. TRG Venture Capital International Investment G.P. Limited screens these issues early. We decline transactions that cannot clear compliance rather than waste client time.
How TRG Venture Capital International Investment G.P. Limited Delivers Results
We combine deep banking relationships with disciplined underwriting. Our team handles instruments from $5 million upward. We arrange both leased and owned SBLCs when the structure meets regulatory standards, yet we prioritise owned instruments for monetization. Clients receive dedicated account managers, encrypted data handling, and clear timelines.
Since 2002 the firm has facilitated more than $2.6 billion in financing. We serve clients across the UK, Europe, Asia, Africa and all over the globe from our base in St Helier, Jersey. Every transaction follows full KYC, AML, and sanctions screening.
FAQ
What advance rate can I expect on a genuine SBLC?
Advance rates usually range from 50 percent to 80 percent of face value. The exact figure depends on the issuing bank’s rating, instrument wording, remaining tenor, and the strength of the repayment source.
Is SBLC monetization the same as selling the instrument?
No. Monetization pledges the SBLC as collateral for a loan or credit facility. The original beneficiary rights usually remain intact unless the parties agree otherwise.
How long does the process take?
Verified instruments with clean documentation can produce funds in 7 to 14 business days. Complex structures or additional legal opinions may extend the timeline.
What documents do I need to start?
You need the full SWIFT MT760 text, details of the applicant and beneficiary, the commercial contract the SBLC supports, and corporate KYC documents. TRG Venture Capital International Investment G.P. Limited provides a complete checklist on first contact.
What happens if the SBLC expires before the facility is repaid?
Facility tenor is always matched to or shorter than the SBLC expiry. Extension language or replacement instruments form part of the documentation when needed.
In Summary
SBLC monetization converts a contingent bank promise into working capital while leaving the original instrument available for its commercial purpose. The process works only with authentic instruments, clear wording, and disciplined counterparties. Advance rates, timelines, and costs vary.
TRG Venture Capital International Investment G.P. Limited has refined this process over more than two decades. We deliver verified capital quickly and transparently. Clients who need liquidity without selling assets or diluting equity find a practical solution here.
#SBLCMonetization #StandbyLetterOfCredit #TradeFinance #ProjectFinance #LiquiditySolutions #TRGVentureCapital
Contact TRG Venture Capital International Investment G.P. Limited today. Share your instrument details through our secure portal. We respond within one business day and provide a clear path to funding. Visit trgventure.capital now. Do not leave capital locked when a verified facility can put it to work.
Contact us @ trgventure.capital
Email: info@trgventure.capital